Ready-to-Move Properties as Investments: Returns, Risks, and Smart Buying Decisions
Explore ready-to-move properties as investments, including potential rental returns, risks, costs, and key factors to consider before buying.
PRIVATE POOLS & AMENITIESCONTRACTSAPARTMENT TYPESRESORT-STYLE COMMUNITIESINVESTMENT PROPERTIESREAL ESTATE BENEFITS
10/6/20265 min read
What Is a Ready-to-Move Property?
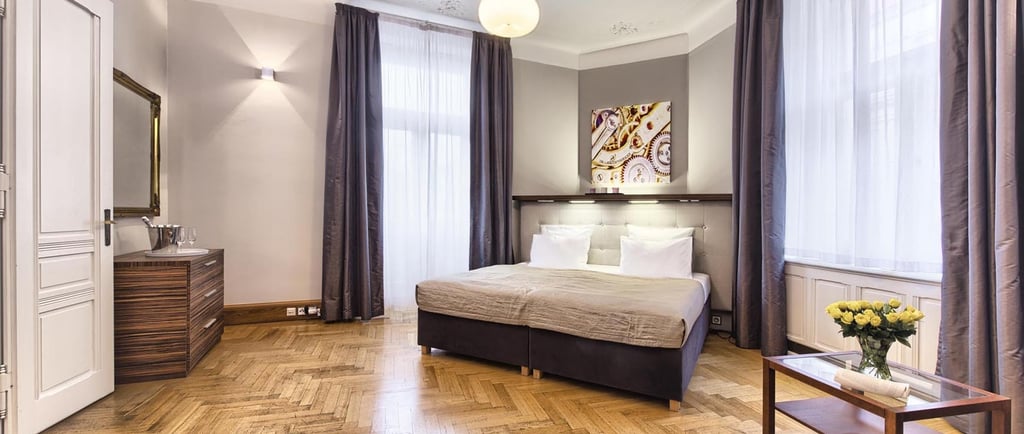
A ready-to-move property is a completed residential unit that can be occupied, rented, or resold immediately. This distinguishes it from an under-construction property, where buyers must wait for construction to finish and accept a degree of uncertainty regarding delivery dates, specifications, and the final appearance. For investors, the absence of a construction waiting period can make financial planning more straightforward. Immediate possession may also reduce the costs associated with temporary accommodation, extended loan interest during construction, or maintaining funds in an asset that produces no income.
Inspect the Actual Property Before Buying
Another advantage is the ability to assess the actual property before making a commitment. Buyers can inspect the apartment’s construction quality, layout, natural light, ventilation, finishes, storage, and views rather than relying primarily on plans, sample units, or developer representations. They can also evaluate completed amenities, parking arrangements, access roads, security systems, common areas, and the surrounding neighborhood. Established surroundings provide useful evidence about connectivity, nearby schools, shops, healthcare facilities, public transport, and the general character of the area. This visibility can help investors identify practical shortcomings that may be difficult to anticipate in a new project still under development.
Start Earning Rental Income Sooner
Ready possession can be particularly attractive to investors seeking immediate rental income and relatively predictable cash flow. Once the purchase is completed and the unit is furnished or prepared for tenants, leasing can begin without waiting for construction or handover. The property may also be resold sooner if market conditions are favorable. However, completion alone does not make a residential property a sound investment. Location, purchase price, rental demand, tenant profile, legal title, occupancy and completion approvals, maintenance charges, property taxes, and future resale prospects require careful review. Investors should compare the expected rental yield and total ownership costs with alternative properties, while considering vacancy risk and the possibility of changing demand. A completed home offers greater visibility and speed, but its investment value still depends on the fundamentals of the market and the quality of the buying decision.
Understand the Financial Benefits of Immediate Possession
Ready-to-move properties can generate financial benefits from the day ownership begins. An investor may occupy the home immediately, avoiding rent paid elsewhere while waiting for construction to finish. Alternatively, the property can be leased without a prolonged handover delay, allowing rental income to start sooner and potentially improving early cash flow. This timing advantage can be especially valuable when loan repayments begin before a property is delivered.
Calculate the Total Cost of a Ready-to-Move Investment
Investment calculations may also be more reliable because the buyer can inspect the completed home, verify its condition, and compare rents with similar occupied properties nearby. Actual listings, lease agreements, and occupancy levels often provide a stronger basis for estimating income than developer projections. Nevertheless, the purchase price is only one part of the acquisition cost. Registration or transfer charges, taxes, brokerage, furnishing, repairs, maintenance deposits, homeowners’ association fees, property management, insurance, and financing interest should all be included in the budget.
Measure Rental Yield and Investment Returns
Several measures help assess whether the expected return justifies the investment. Gross rental yield compares annual rent with the purchase price, while net rental yield deducts operating expenses and recurring charges. Investors can also estimate potential appreciation, cash-on-cash return, and the loan-to-value ratio, which indicates how heavily the purchase depends on borrowed funds. Vacancy-adjusted income is particularly important: projected rent should be reduced to reflect possible empty periods, tenant turnover, and collection delays.
Compare Ready-to-Move and Under-Construction Properties
Completed homes may provide more stable short-term returns because rental demand, property condition, and immediate expenses are easier to observe. However, an under-construction property bought early in a high-growth area may deliver greater appreciation if infrastructure and demand develop as expected, although it carries construction and delivery risks. A balanced decision compares annual income, costs, financing exposure, and long-term value with safer alternatives such as bank deposits, bonds, or diversified investments. The property should offer compensation for its illiquidity, management demands, and market uncertainty.
Consider the Higher Purchase Price of Completed Properties
Ready-to-move properties can offer immediate possession, but that convenience often comes at a price. Completed homes generally include a possession premium, meaning investors may pay more per square foot than they would for a comparable early-stage unit. Since construction risk has already been absorbed by the developer, there may also be less room for negotiation. The higher entry cost can reduce potential capital appreciation and make it harder to achieve an attractive rental yield.
Assess Supply, Vacancy, and Ongoing Ownership Costs
Supply conditions require equal attention. In an oversupplied neighborhood, numerous similar units may remain vacant, forcing owners to reduce rent or offer incentives to attract tenants. Excess inventory can also slow resale, particularly when buyers have many comparable properties to choose from. Ownership costs further affect returns. Maintenance charges, property taxes, repairs, furnishing, insurance, utility-related expenses, and association fees can consume a substantial share of rental income. Investors must also account for tenant turnover, vacancy periods, delayed payments, and professional management fees when they cannot oversee the property personally.
Complete Legal and Property Due Diligence
Thorough due diligence is essential before committing funds. Buyers should verify ownership records, title history, approved building plans, completion and occupancy certificates, construction permits, outstanding dues, mortgage encumbrances, association rules, and utility connections. The developer’s or seller’s reputation should be assessed independently rather than based only on sales materials. A property that appears complete can still contain unresolved legal defects, unauthorized alterations, poor workmanship, or structural concerns. Qualified legal, technical, and financial professionals can help identify issues that are difficult for a non-specialist to detect.
Understand the Market Risks of Property Investment
External market risks may also reduce profitability. Rising interest rates can increase borrowing costs, while an economic downturn may weaken rents and property values. Neighborhood decline, changing tenant preferences, and inadequate infrastructure can reduce demand over time. Finally, limited liquidity is a significant concern: an investor who needs a quick sale may have to accept a discount, especially when competing properties are plentiful or market sentiment is weak.
Define Your Investment Objective Before Buying
The decision should begin with a clearly defined investment objective. An investor seeking immediate rental income may value a completed home that can be occupied or leased without construction delays. Someone focused on capital appreciation may place greater importance on future infrastructure, employment growth, and land scarcity. Other objectives may include retirement use, portfolio diversification, or eventual personal occupancy. The preferred property should support the intended time horizon rather than simply appear attractive at the point of purchase.
Evaluate Location and Rental Demand
Location requires evaluation beyond appearance and advertised amenities. Examine access to employment centers, public transportation, schools, healthcare, retail, and essential services. Review planned roads, transit links, commercial developments, and other infrastructure, while also considering safety and neighborhood stability. Evidence of sustained tenant demand is particularly important. Rental occupancy, the duration of listings, tenant profiles, and the performance of comparable buildings can indicate whether demand is dependable or merely seasonal.
Compare Ready-to-Move Properties With Realistic Alternatives
Compare the property with realistic alternatives using identical assumptions. Assess purchase price, achievable rent, vacancy, maintenance, management fees, insurance, taxes, utilities, financing costs, and expected appreciation. Calculate net returns after every recurring and one-time expense, rather than relying on gross rental yield. Advertised rents can be optimistic, so verify them through recent leases, rental listings, property managers, and available transaction data. A seemingly cheaper alternative may produce stronger returns if it has lower operating costs or more consistent occupancy.
Inspect the Property and Review Building Management
Due diligence should include inspecting the completed unit, finishes, fixtures, plumbing, electrical systems, ventilation, storage, parking, and common areas. Speak with existing residents where possible and review building maintenance, service charges, defect records, and management practices. Confirm ownership, approvals, completion documents, service obligations, and any restrictions affecting leasing or resale.
Keep an Emergency Reserve and Manage Investment Risk
Maintain an emergency reserve for vacancies, repairs, and unexpected assessments, and avoid excessive borrowing that depends on uninterrupted rent or rising prices. A ready-to-move property can be the better investment when immediate income, certainty, and transparency are priorities, but it is not automatically superior. The final choice should rest on disciplined valuation, verified documents, strong local demand, and a clear fit with the investor’s risk tolerance and time horizon.